Article
Why X Money Is the Most Underrated Product on the X App
13 Oct 2026
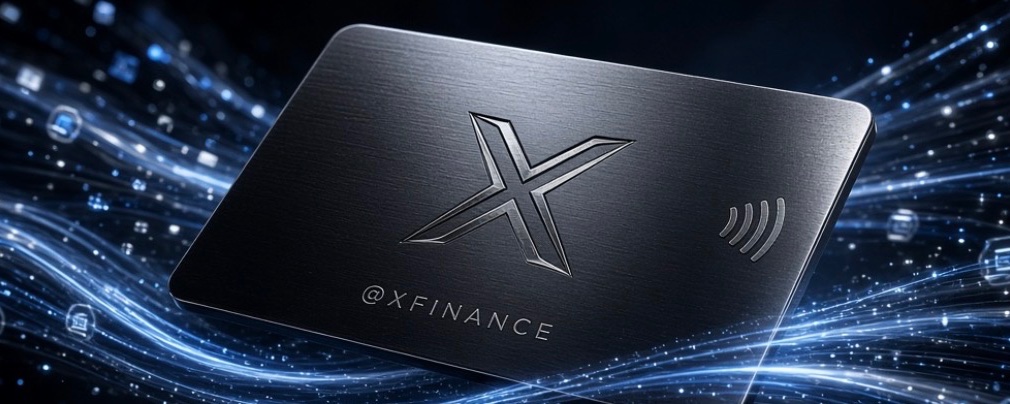
X Money launched as a payments and stored-value product inside the X app and has expanded well beyond its early beta.
X Money launched as a payments and stored-value product inside the X app and has expanded well beyond its early beta. It combines an interest-bearing cash account, a Visa debit card (virtual and physical metal), instant peer-to-peer transfers, and deep integration with the platform itself. Many users still treat it as an optional add-on. That understates what it actually delivers for everyday cash management, spending rewards, and creator earnings.
Here is a clear look at the features that make it stand out, based on current terms and how the product works in practice.
Local Cash Deposits and Everyday Convenience
You do not need a traditional bank branch. X Money supports cash loads at thousands of participating retailers. Open the Money section, select Deposit then Cash, generate a barcode, and hand the cash to the cashier. Funds typically appear in minutes.
Participating locations commonly include pharmacies, convenience stores, and similar retail partners (users have reported networks that include places like CVS, Family Dollar, and 7-Eleven-style stores). I just made a "deposit" at my local Walgreens. I had to teach the cashier how to do it, but it was fun for both of us! This is useful if you are paid in cash, receive tips, or simply want to move physical money into the app without waiting on ACH.
You also get mobile check deposit, (got to hunt for it, it's like the cash) ACH and debit-card funding, early direct deposit (up to two days early on qualifying payroll), bill pay, mailed checks, and wires. Everything lives in the same Money tab where you already spend time on X. Recent Activity shows your full transaction history in the app. Certain items, such as creator payouts, can be shared directly to the timeline from the Activity view. A dedicated Money area has also begun appearing in Notifications (This is where mine is), keeping payments, transfers, and account updates in one place alongside your regular feed.
Get Paid to Spend Your Working Capital
Most debit cards pay little or nothing in rewards. X Money’s X Card pays up to 3% cash back on eligible purchases. Premium and Premium+ users receive the 3% rate outright. Other users can reach the boosted rate after $1,000 or more in qualifying deposits within a trailing 34-day period. Qualifying deposits include certain ACH direct deposits (SEC code PPD) and X creator payouts.
The cash-back is not unlimited in every category—utilities, rent, certain wholesale clubs, (this one's a bummer because i buy my gas at Costco so no cash back on one of my biggest expenses!) , taxes, government services, jewelry, and some other merchant types are excluded—but for ordinary everyday spending, like groceries and home improvements, it is unusually strong for a debit product. The idea is straightforward: if you are already spending your cash flow, the account should return something rather than letting the value sit idle.
Up to 6% APY on Cash Balances
Balances earn up to 6.00% APY. Premium+ users receive the 6% rate as standard. Other users start at 4% and can reach the boosted 6% rate with the same $1,000+ qualifying-deposit requirement noted above. Rates are variable and can change. New York residents are currently ineligible for the APY (the product has offered alternative incentives in that state).
For a liquid cash account with no minimum balance required to open and use the core features, 4–6% is competitive with many high-yield savings options and well above the national average for ordinary savings or checking. Combined with the cash-back, idle money and spending both work harder than they do in a standard bank account that pays near-zero interest and zero debit rewards.
The Metal Card as a Quiet Statement Piece
The physical X Card is a metal Visa debit card. It makes a really nice clink on the table, which to be honest, i kinda like.
Premium and Premium+ users receive it free; others can order it for a fee. It carries your X handle and has no printed number, expiration, or CVV on the face (details live in the app). A virtual card is issued immediately and can be added to Apple Pay or Google Pay.
Most people will never see the physical card. For anyone in sales, client-facing work, high-visibility networking, or situations where the card comes out at a restaurant or meeting, the metal finish and handle engraving read as intentional rather than generic. It is accepted anywhere Visa is accepted, carries no foreign transaction fees, and includes ATM fee reimbursements (unlimited for Premium and Premium+; limited for others).
Send Anyone on X Money Instantly, Anytime
Peer-to-peer transfers to other X Money users are free and, once identity is verified, have no transaction limits. You search for the handle or scan a QR code inside the app. The money moves instantly in the vast majority of cases. You can also request money. This removes the need to leave the app, open a separate payment service, or deal with fees and delays for transfers between people who already interact on X.
Creator Payments Land Immediately and Are Required for U.S. Accounts
For U.S. creators, payouts from Original Content Rewards and creator Subscriptions now route through X Money. This is mandatory for stateside accounts; non-U.S. creators continue on the previous path. There is no $30 minimum and no biweekly waiting period—funds are available when sent.
Those payouts also count as qualifying deposits toward the boosted APY and cash-back tiers. Creators who were already using the platform’s monetization tools effectively seed their X Money balance automatically and can spend or transfer the funds the same day.
Additional Practical Advantages
- Funds are held at Cross River Bank (Member FDIC) with standard coverage up to $250,000. Eligible users are enrolled in the Cash Sweep Program, which can extend aggregate pass-through coverage significantly higher by distributing balances across partner banks.
- No foreign transaction fees and ATM fee reimbursements.
- Passkey security, custom transaction limits, and Visa Zero Liability protection on the card.
- 24/7 support options.
- Joint accounts and beneficiary features have begun appearing in limited form.
- The entire experience stays inside the X app and on X.com—no separate banking login required for core actions.
Who It Fits Best
X Money is strongest for people who already live on the platform, receive creator or subscription income, want high yield on cash they plan to spend or transfer, value instant free sends to other users, and like the idea of cash-back on debit spending. It is less ideal as a complete replacement for every banking need (for example, large cash deposits have daily limits, certain categories do not earn cash-back, and availability is currently U.S.-focused with some state restrictions).
Rates, cash-back eligibility, and features can change, and the product is not a bank itself—X Payments LLC partners with regulated institutions. Still, for an offering that sits inside the social app where many users already spend significant time, the combination of yield, rewards, instant transfers, local cash loads, and mandatory fast creator payouts is more complete than most people expect.
If you spend your working capital, get paid on X, or simply want your cash and everyday transactions to live in the same place as your feed, X Money is worth opening and testing. The metal card and the 3% cash-back are nice; the combination of convenience, speed, and return on cash is what makes it the most underused product currently sitting in the app.
So that's it, that's my story, and this isn't a paid promotion, so products actually are good enough to just talk about, hopefully X can do a better job getting the word out!
The Hood $35. Buy